Conversational AI for Insurance
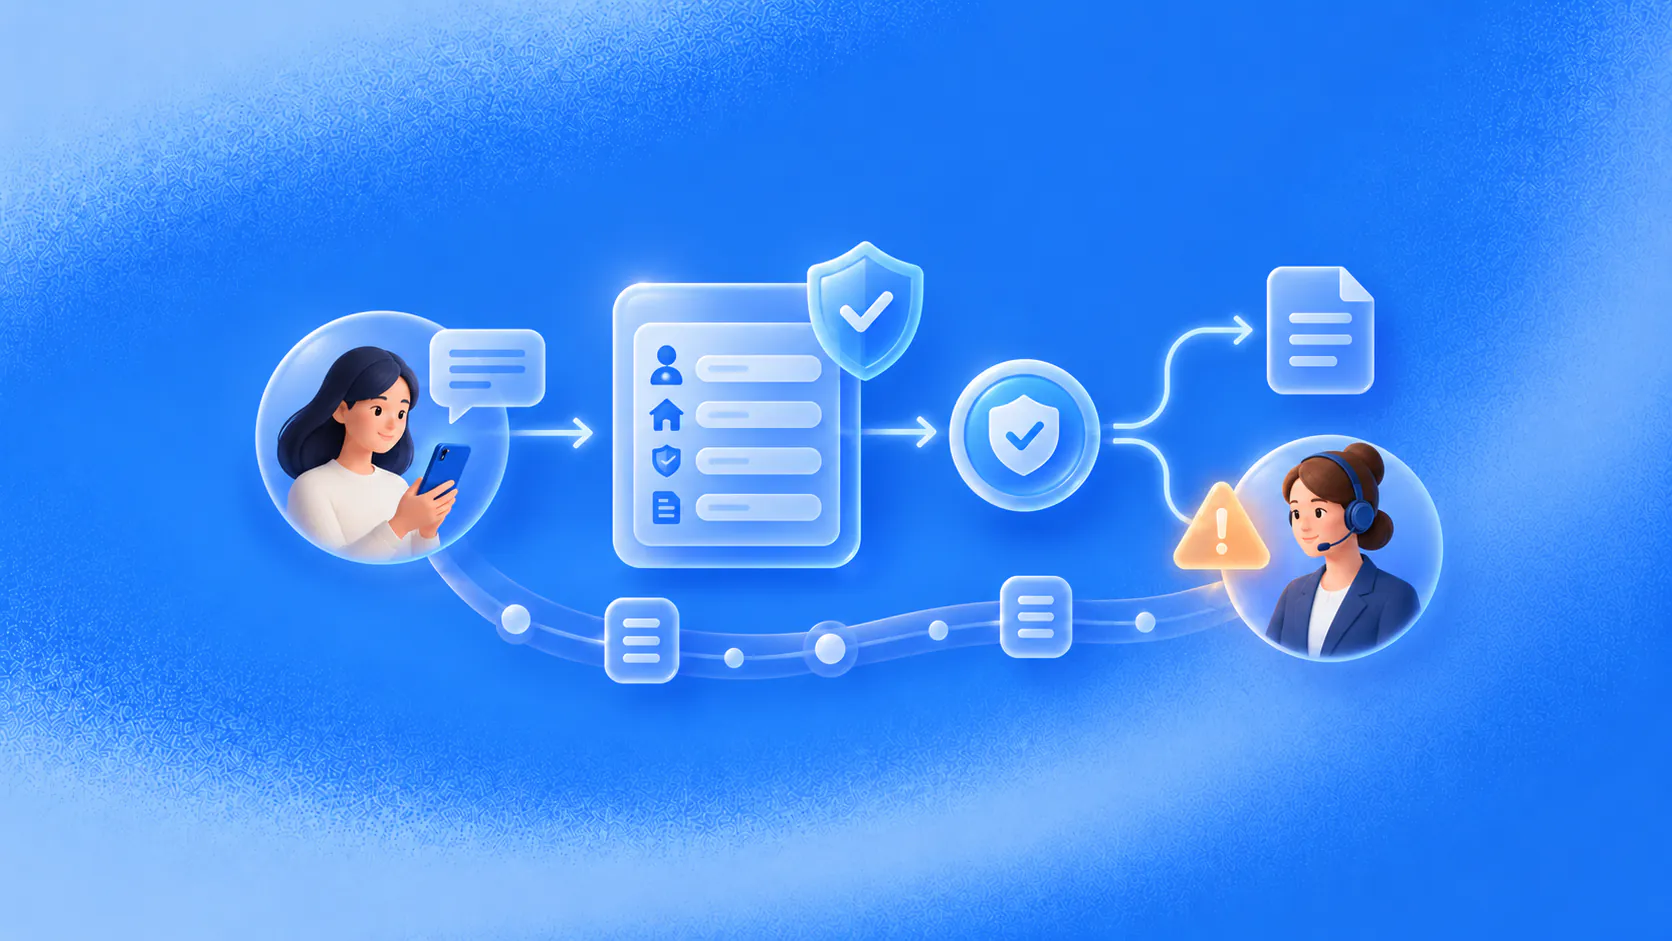
Conversational AI in insurance can provide approved policy-process information, collect service or claim-notification details, share status from connected systems, send reminders and route customers to licensed or authorised staff. It should not make unreviewed coverage, underwriting or claim decisions.
Key takeaways
- Separate general process information from customer-specific coverage or claim decisions.
- Use conversational intake to collect and route information, not to make unsupported determinations.
- Verify identity and permissions before revealing policy or claim details.
- Keep licensed, authorised or specialist staff responsible for advice, exceptions and consequential decisions.
What is conversational AI in insurance?
Conversational AI in insurance helps customers and prospects navigate approved information and service workflows through ordinary language. It can answer general process questions, collect a service request, record first notice of loss information, retrieve a status from a permitted system and connect the customer with the right team.
The boundary matters. Insurance involves consequential decisions, licensed activities and jurisdiction-specific obligations. A conversational interface should not be assumed to decide coverage, underwriting, claim liability or suitable products.
Use it to improve access and workflow continuity while keeping authorised people and governed systems responsible for decisions.
Related must-read articles
- Conversational AI for customer support
- Insurance AI agents
- How AI supports insurance claims and onboarding
Which insurance workflows are suitable?
Conversational AI in insurance can support bounded administrative and service tasks where the information source, permissions and owner are clear.
General process information
The assistant can explain how to report a claim, update contact details, request documents or reach a team using insurer-approved content. It should distinguish general guidance from advice about a specific policy.
Policy-service requests
After the appropriate verification, a customer may request a document, update, payment-process explanation or contact from an adviser. The system can collect the request and complete only actions the insurer has approved.
First notice of loss intake
A conversation can collect required incident and contact details and create a case for review. This is intake, not a decision about coverage or outcome.
Claim or service status
With limited access, the system may retrieve and explain the recorded stage of a case. It should not infer what will happen next beyond the approved process and data returned.
Renewal communication
The system can send consent-aware reminders, explain administrative steps and route questions to authorised staff. It should stop or change the sequence when the policy state changes.
How should general information differ from policy-specific answers?
A general source might describe the documents commonly requested for a claim type. Whether a specific customer’s loss is covered depends on the policy, facts, applicable rules and authorised decision process.
Conversational AI in insurance should state which kind of answer it is providing. If the customer asks, “Am I covered?”, the system can locate the relevant service path and arrange review rather than generate a conclusion from generic content.
Approved knowledge sources need owners, effective dates, jurisdiction and audience. Outdated policy language can be more harmful than no answer.
What does a claim-intake scenario look like?
Imagine a customer reporting vehicle damage. The assistant explains that it can collect initial information for the claims team. It follows the insurer’s verification and consent process, then asks for the incident date, location, a factual description and contact details.
It creates a first-notice record and returns the reference supplied by the claim system. It provides the approved next-step message and document route.
If the customer reports an injury, distress, a legal dispute or another specialist condition, the workflow follows the insurer’s approved escalation procedure. It does not assess liability, predict the claim result or advise on medical or legal action.
That separation allows conversational AI in insurance to reduce intake friction without taking responsibility it should not have.
How can policy servicing work?
Policy servicing may include address changes, document requests, beneficiary or named-party requests, billing questions and cancellation enquiries. Each task needs its own verification, permission and approval model.
Some actions can complete automatically after verification; others should create a reviewed request. The customer must be told which state applies.
“Your address has been updated” requires a successful system response. “Your request has been sent for review” is not the same outcome. The workflow layer should store that state and the returned evidence.
How should renewal and retention messages be controlled?
Renewal communication should use the current policy state, permitted timing and channel consent. Stop reminders when the policy renews, lapses, cancels or moves to a specialist queue.
Conversational AI can answer approved process questions and collect a request for an adviser. It should not recommend coverage or present a product as suitable without the required licensed and governed process.
The renewal-reminder guide explores the messaging workflow. The broader guide to conversational AI for customer retention explains suppression, consent and outcome measurement. Any performance claim needs reliable evidence and appropriate attribution.
What needs immediate human ownership?
Define routing for:
- Coverage, underwriting or claim-decision questions;
- Customer vulnerability or distress;
- Injury, safety or urgent circumstances;
- Complaints and disputes;
- Suspected fraud or identity conflict;
- Legal or regulatory questions;
- Failed system actions;
- Requests for a licensed or authorised person.
The receiving team needs the customer’s stated goal, verification state, information collected, system actions and reason for handoff. Human handoff should preserve that context without exposing data beyond the role’s access.
The customer-support guide explains how to prepare that transfer, while the omnichannel guide covers identity and continuity when the request changes channel.
How should identity, privacy and security be handled?
General public information may require no customer identification. Policy details, claim status and account actions require stronger controls.
Define the verification level for each action. Limit system permissions, mask or avoid unnecessary sensitive data and set access and retention policies for transcripts and structured fields.
Requirements vary by market, insurance product and operating model. Obtain appropriate legal, compliance, security, privacy and licensed subject-matter review. Do not present a platform feature as proof of regulatory compliance.
Which metrics are useful?
Measure service performance without implying a claim or financial outcome:
- General questions answered from an approved source;
- Service requests completed or correctly submitted;
- First-notice records accepted by the claim system;
- Status requests completed after verification;
- Action failures and recovery;
- Customer or handler corrections;
- Routing accuracy and time to human ownership;
- Repeated contacts about the same request.
Review samples of resolved and failed conversations. A lower handoff rate is not automatically better if customers cannot reach authorised help.
How should insurers implement the first workflow?
Begin with one low-ambiguity process, such as general claim-reporting information or collection of a callback request. Document sources, verification, fields, permissions, completion evidence and exception owners.
Test ambiguous policy questions, incorrect identity details, vulnerable customers, tool outages, complaints, requests outside scope and direct requests for a person. Pause expansion until the operating team can explain and correct failures.
The implementation guide provides a staged method. ZINQ’s insurance industry page and follow-up use case show how customer conversations can connect with approved workflows and handoff while decision responsibility stays visible.
What should an insurance control review cover?
Create an authority matrix before conversational AI in insurance is configured. For every intent, state whether the assistant may provide information, collect details, read a status, submit a request or only route the customer.
Attach a source and owner to every answer, including product, jurisdiction, audience and effective date. If the applicable version is uncertain, the assistant should not combine language from several policies.
Test a request for a coverage decision, conflicting identity details, vulnerability or distress, injury, a legal dispute, a policy-party change, an unavailable claim status, a complaint and a request for authorised staff.
Review the appropriate transcripts with claims, service, legal, compliance, privacy and security stakeholders. Their role is to verify boundaries and process, not approve generic assurances.
Conversational AI in insurance needs a traceable correction path. Record the source, rule and workflow behind a wrong answer or route, then add the example to evaluation. Conversational AI in insurance should expand only after owners can account for content, permissions, exceptions and monitoring.
Frequently asked questions
How can insurers use conversational AI?
They can use it for general process information, policy-service requests, first notice of loss intake, document checklists, claim status, renewal reminders and routing to the appropriate team.
Can an insurance chatbot decide whether a claim is covered?
This guide does not recommend unreviewed coverage decisions. The system may explain approved general information or display a recorded status, while authorised staff and governed systems retain decision responsibility.
What information can it collect for a claim?
It can collect fields approved for first notice of loss or service intake, such as policy reference, incident details and contact information, subject to identity, privacy, security and legal controls.
How should sensitive cases be handled?
Route injury, vulnerability, dispute, fraud concern, complaint, legal question, unclear coverage or customer distress to the appropriate trained team under approved procedures.
Conclusion
Conversational AI in insurance should improve access to service without obscuring who makes consequential decisions. Keep sources approved, customer data protected, actions confirmed and licensed or authorised people responsible for exceptions.
READY TO SEE ZINQ IN ACTION?
From first enquiry to conversion, follow-up and support, ZINQ helps automate the next step while keeping your team in control.
Book a DemoAdditional resources
-
Insurance AI Agent: Intake, Service and Handoff
An insurance AI agent supports controlled communication workflows such as approved information, structured intake, status updates and routing, while coverage, eligibility, underwriting and claims decisions remain with authorised systems and people.
The ZINQ team · October 7, 2026 · Industries → Insurance -
AI in insurance onboarding and claims communication
AI can assist insurance onboarding and claims communication by explaining approved steps, collecting required information and retrieving authorized status updates. Coverage decisions, settlement judgments and advice need the insurer's appropriate review process.
Pavan · June 22, 2026 · Industries → Insurance -
Insurance renewal reminders: workflow, templates and metrics
Insurance renewal reminders work best when they help customers review their renewal, ask questions and complete the next step. Build the workflow around current policy information, a useful message sequence and a clear route to your servicing team. Stop or change the sequence as soon as the customer's situation changes.
Pavan · August 11, 2026 · Industries → Insurance